San Diego Short Sale Help
Experienced Guidance When You Owe More Than Your Home May Sell For
If you are struggling with mortgage payments, facing a financial hardship, or concerned that you owe more than your San Diego property can sell for, you may be wondering whether a short sale could provide a way forward.
A short sale is not an ordinary real estate transaction. It involves selling a property for an amount that may be insufficient to pay the mortgage debt and other approved costs in full. Because one or more lenders must agree to accept less than the amount owed and release their liens, the sale generally cannot close without the required lender approvals.
The process can involve detailed financial documentation, strict deadlines, multiple lienholders, property valuation reviews, buyer negotiations, lender conditions, and extensive communication. That is why choosing an experienced San Diego short sale agent is so important.
Dawn Lewis and The Lewis Team at Real Broker provide experienced, responsive guidance to San Diego homeowners considering a short sale. We help owners understand the real estate side of the process, prepare the property for the market, assemble the transaction package, communicate with the mortgage servicer or its authorized representatives, negotiate with buyers, coordinate documentation, and work toward an approved closing.
Every homeowner's situation is different, and a short sale is not automatically the right solution. The first step is to examine your property, mortgage obligations, timing, goals, and available options carefully.
For confidential San Diego short sale help, call Dawn Lewis and The Lewis Team at 619-656-0655.
What Is a Short Sale?
A short sale occurs when a property is sold and the net sale proceeds are expected to be less than the total amount required to pay the mortgage liens and approved closing expenses. The word “short” refers to the shortage in the payoff—not the length of the transaction.
For example, a homeowner may owe more on a first mortgage, second mortgage, home-equity line, delinquent association account, or other lien than the property can reasonably sell for after closing costs. If the seller cannot bring enough money to closing to cover that shortage, approval may be requested from the affected creditor or creditors.
The owner still holds title and remains the seller. The property is marketed to buyers, an offer is negotiated, disclosures are completed, and escrow is opened much like a conventional sale. The significant difference is that the lender or lienholder must review the proposed transaction and decide whether to approve the reduced payoff and lien release.
A lender is not required to approve a short sale. Approval terms vary according to the loan, investor, servicer, property, hardship, valuation, offer, liens, program requirements, and applicable law. No real estate agent can guarantee approval, a particular timeline, debt forgiveness, relocation assistance, or a specific effect on credit or taxes.
When Might a San Diego Homeowner Consider a Short Sale?
Homeowners explore short sales for many reasons. A financial change may make the existing mortgage difficult to maintain, or a necessary sale may coincide with insufficient equity.
Circumstances can include:
- Loss or reduction of household income
- Increased mortgage payments or other housing expenses
- Medical or caregiving expenses
- Divorce or separation
- Job transfer or relocation
- Death of a contributing owner or household member
- A required move combined with insufficient equity
- Significant deferred maintenance or repair costs
- Delinquent mortgage payments
- An approaching foreclosure timeline
- A property value below the total debt and selling expenses
- Unsuccessful efforts to obtain another loss-mitigation solution
Missing payments is not the definition of a short sale, and a homeowner does not necessarily need to wait until foreclosure activity begins before requesting information. Requirements vary by servicer and investor. Contacting qualified professionals early generally provides more time to examine alternatives, collect documents, market the property, and respond to lender deadlines.
A Short Sale Should Begin With a Review of Your Options
A short sale is one possible response to mortgage difficulty, but it is not the only one. Depending on the homeowner, loan, income, hardship, property, and servicer, other possibilities could include a repayment plan, forbearance, loan modification, refinance, reinstatement, conventional sale, deed in lieu of foreclosure, or another available loss-mitigation option.
Homeowners who want to keep their property should contact their mortgage servicer promptly to ask about available programs. A HUD-approved housing counselor can also provide foreclosure-prevention counseling. HUD states that foreclosure-prevention counseling is available without charge through approved agencies.
The Lewis Team helps homeowners evaluate the property and real estate transaction, but we do not provide legal, tax, bankruptcy, lending, or credit-repair advice. Before deciding on a short sale, an owner should consider speaking with an attorney, qualified tax professional, HUD-approved housing counselor, and other appropriate advisors. This is particularly important when there are multiple liens, judgments, unpaid association charges, divorce proceedings, probate issues, bankruptcy, pending foreclosure activity, or questions about personal liability.
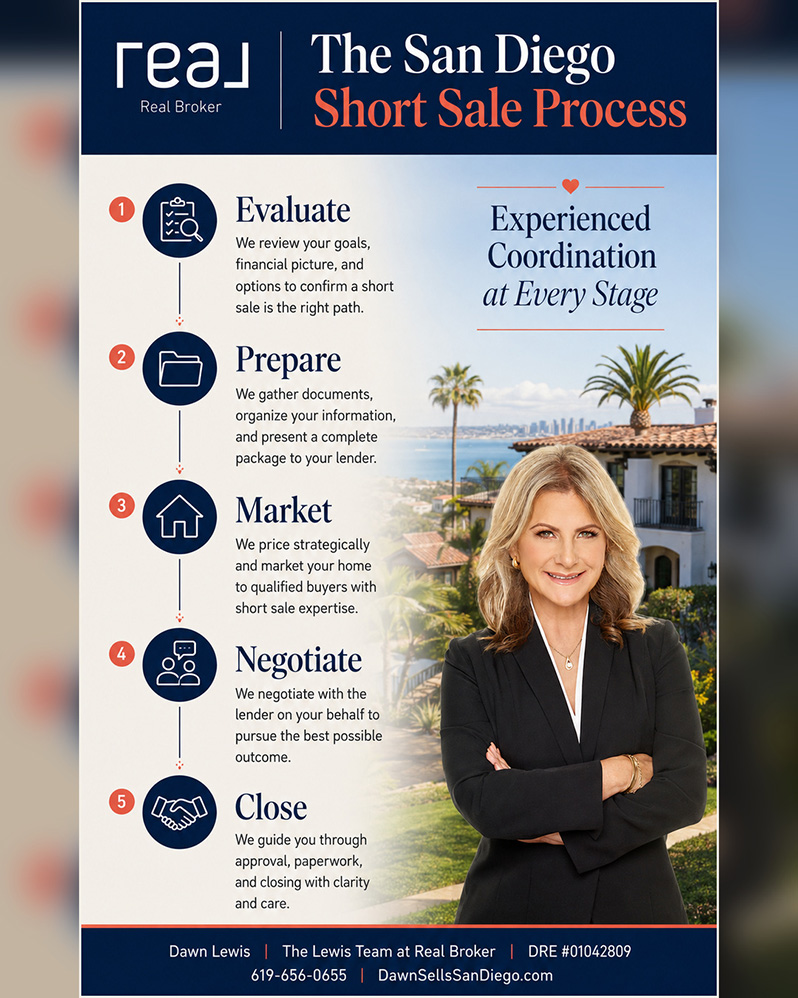
The San Diego Short Sale Process
No two short sales follow exactly the same path. The following overview explains the typical stages, but the lender may change its requirements or request additional information.
1. Initial Confidential Consultation
The process begins with a conversation about the property and the owner's situation. Dawn will ask questions such as:
- Where is the property located?
- What type of property is it?
- Who holds title?
- How many mortgage loans or other liens may exist?
- What are the approximate loan balances?
- Are payments current, late, or in active foreclosure proceedings?
- Has a Notice of Default or Notice of Trustee's Sale been received?
- Is there an HOA, and are the dues current?
- Is the property owner-occupied, vacant, tenant-occupied, or used as a rental?
- What repairs or maintenance issues are present?
- Why does the owner need or want to sell?
- Has the servicer offered or denied another loss-mitigation option?
This conversation helps identify urgency, possible complications, and the documents that may be needed. It is helpful to provide accurate information from the beginning. Unknown liens or deadlines discovered late can threaten an otherwise workable transaction.
2. Preliminary Property and Mortgage Review
Dawn and The Lewis Team will examine the property's likely market position using relevant comparable sales, active listings, pending competition, location, condition, improvements, parking, lot or unit characteristics, and current buyer demand.
The goal is to establish a defensible asking-price strategy. Pricing too high can prevent qualified buyers from submitting offers. Pricing far below market value can cause the lender to reject the transaction or demand a higher price.
The preliminary review may also identify title, HOA, tenant, condition, solar, permit, or access issues that require additional attention. A title and lien review is essential because a first mortgage may not be the only obligation that must be addressed.
3. Contacting the Mortgage Servicer
The homeowner normally contacts the mortgage servicer to ask about its short-sale or loss-mitigation procedures. The servicer may require written authorization before discussing the account with Dawn, a negotiator, escrow, or another authorized participant.
The owner should continue opening and reviewing every communication from the servicer, foreclosure trustee, HOA, taxing authority, court, and insurance provider. Listing a property or submitting a short-sale package does not automatically stop a foreclosure. Any sale date or legal deadline requires immediate attention from the appropriate professionals.
4. Preparing the Short-Sale Package
The lender typically requests a detailed package. Requirements vary, but documents may include:
- Borrower authorization
- Lender-specific application or loss-mitigation forms
- Hardship letter or hardship explanation
- Recent bank statements
- Recent pay stubs or proof of income
- Tax returns or signed tax forms
- Monthly income-and-expense statement
- Mortgage statements
- HOA statements
- Evidence of hardship
- Listing agreement
- Purchase contract and addenda
- Estimated settlement or closing statement
- Preliminary title report
- Comparable-market information
- Property photographs
- Repair estimates when relevant
- Buyer qualification or proof of funds
- Arm's-length transaction certification
Documents must be complete, accurate, current, and consistent. Missing pages, unsigned forms, outdated financial statements, or unexplained deposits can delay review. The servicer may request updated documents more than once because financial paperwork often expires during the process.
Never alter or conceal information. Material facts, relationships between transaction participants, payments, credits, and agreements must be disclosed as required. The lender's arm's-length and anti-fraud requirements must be taken seriously.
5. Preparing and Marketing the Property
A short-sale home should still be marketed professionally. Buyers and lenders need evidence that the property received reasonable exposure and that the accepted offer reflects current market conditions.
The Lewis Team can develop a customized marketing plan that may include:
- Professional property photography
- Accurate and persuasive listing copy
- Placement in the applicable multiple listing service
- Distribution to major real estate websites
- Buyer-agent outreach
- Digital and social-media marketing
- Showing coordination
- Feedback monitoring
- Offer analysis and negotiation
The marketing should explain the property's strengths without hiding defects or misrepresenting the short-sale approval requirement. Required disclosures remain important in a short sale. Selling for less than the mortgage balance does not eliminate a seller's disclosure obligations.
6. Reviewing and Accepting a Buyer's Offer
The seller—not the lender—typically selects and accepts an offer subject to short-sale approval. The best offer is not always the one with the highest headline price. Important considerations include:
- Purchase price
- Buyer's financing and qualification
- Cash contribution and proof of funds
- Deposit
- Inspection and appraisal terms
- Requested credits or repairs
- Closing timeline
- Short-sale approval contingency
- Ability to remain committed during lender review
- Other transaction-specific terms
Once the seller accepts an offer, the complete transaction package is submitted for lender consideration. The contract should clearly address the short-sale contingency and the fact that lender approval may be required.
7. Lender Review and Property Valuation
The servicer reviews the homeowner's eligibility, financial documentation, hardship, title information, proposed settlement statement, buyer's offer, and transaction terms. It may order a broker price opinion, appraisal, automated valuation, or another evaluation of the property's market value.
The lender may:
- Approve the offer and proposed terms
- Request additional or updated documents
- Require a higher sale price
- Change allowable closing costs
- Limit credits or concessions
- Request a seller contribution when permitted
- Negotiate payments to junior lienholders
- Deny the request
- Close the file if deadlines or document requirements are missed
If more than one lienholder is involved, each affected creditor may require separate review and approval. HOA liens, judgments, tax liens, solar obligations, and other claims can complicate the settlement. An approval from the first mortgage holder does not necessarily resolve every other lien.
8. Short-Sale Negotiation
This stage requires persistence, organization, and careful communication. Dawn and The Lewis Team track the real estate transaction, respond to requests within the permitted scope of representation, keep the buyer's agent informed, coordinate updated documentation, and work with escrow and other participants.
The objective is to demonstrate that the offer reflects the property's current market value and that the proposed closing is a reasonable resolution. If the lender counters, Dawn can help the seller evaluate the real estate terms and negotiate with the buyer when appropriate.
Lender review can take weeks or months. Timing depends on the servicer, investor, loan type, number of liens, completeness of the package, valuation, foreclosure status, buyer, and transaction complexity. A homeowner should not rely on a promised approval date unless it is confirmed in writing by the authorized decision-maker.
9. Reviewing the Written Approval
Verbal statements are not enough. Before moving toward closing, the seller should receive and carefully review the written approval terms.
The approval letter may address:
- Approved purchase price and net proceeds
- Closing deadline
- Allowed commissions and closing expenses
- Payments to junior lienholders
- Seller contributions
- Repair or credit limitations
- Whether the seller may receive any funds
- Treatment of the remaining loan balance
- Continuing obligations, if any
- Required affidavits or certifications
The wording concerning the unpaid balance can be extremely important. Sellers should have an attorney review legal questions and a qualified tax professional review possible tax consequences. Dawn can explain the real estate transaction, but she cannot provide a legal opinion about liability or a tax opinion about canceled debt.
10. Inspections, Appraisal, and Final Buyer Approval
Lender approval does not eliminate the buyer's contractual investigation or financing requirements. Depending on the agreement, the buyer may conduct inspections, review disclosures and HOA documents, obtain an appraisal, and complete loan underwriting.
Short-sale lenders frequently limit repairs and seller-paid credits. The property may be sold in its present condition, subject to the contract and applicable disclosure requirements. If an inspection reveals a major issue, any renegotiation may require additional lender approval.
11. Escrow and Closing
Escrow must follow the short-sale approval letter precisely. The closing statement, lien payments, commissions, credits, contributions, and closing date must be consistent with approved terms.
If the approval expires before closing, an extension may be required. Extensions are not automatic. Organized coordination among the seller, buyer, agents, escrow, title company, lenders, and other participants is critical.
At closing, title transfers to the buyer and approved funds are distributed. The seller should retain the approval letter, closing statement, loan correspondence, tax documents, and other records for future reference.
What Can Make a Short Sale More Complicated?
Several conditions can add time or additional approvals:
- Two or more mortgage loans
- Home-equity lines of credit
- HOA delinquencies or liens
- Property-tax liens
- Judgments or other recorded claims
- Solar leases or financing agreements
- Federal, state, VA, FHA, or investor-specific requirements
- Mortgage insurance
- Bankruptcy or probate proceedings
- Divorce or disagreements between owners
- Tenant-occupied property
- Major property damage
- Unpermitted work
- A scheduled foreclosure sale
- Incomplete financial documents
- Buyer cancellation during lender review
- A lender valuation above the accepted price
Complications do not necessarily make a short sale impossible. They do make early investigation and experienced coordination more important.
Do You Have to Miss Mortgage Payments to Qualify?
Not necessarily. A lender's requirements depend on the loan, investor, servicer, hardship, and available program. Some homeowners request assistance before becoming delinquent; others seek help after missing payments or receiving foreclosure notices.
A real estate agent should not instruct an owner to stop making mortgage payments. That is a serious financial and legal decision. Homeowners should discuss payment questions directly with their servicer and appropriate financial, legal, or housing-counseling professionals.
Can a Short Sale Stop Foreclosure?
A short sale may be pursued as an alternative to foreclosure, but merely listing the property, accepting an offer, or submitting a package does not guarantee that foreclosure activity will stop. The homeowner must continue monitoring all notices and deadlines.
If a trustee's sale has been scheduled, the situation is urgent. The owner should immediately contact the servicer and consult qualified legal counsel regarding available rights and deadlines. Dawn and The Lewis Team can move quickly on the real estate portion, but only the lender, trustee, court, or another authorized party can confirm the status of foreclosure activity.
Will the Lender Forgive the Remaining Balance?
The answer depends on the written approval, loan type, lienholder, applicable law, and specific facts. California law provides certain anti-deficiency protections for qualifying short sales, but exceptions and other obligations may apply. The approval letter must be reviewed carefully, and homeowners should obtain legal advice concerning their own liability.
Do not assume that a lien release and a release of personal liability are automatically the same thing. The seller should understand exactly what each creditor is approving before closing.
Are There Tax Consequences After a Short Sale?
There may be. The IRS explains that canceled debt is generally taxable unless an exception or exclusion applies. A creditor may issue Form 1099-C after canceling debt. A property transfer may also create a reportable gain or loss depending on the debt, property, adjusted basis, and other circumstances.
Federal and California rules can change, and their application depends on the homeowner's facts. Sellers should consult a qualified tax professional before completing a short sale and again when preparing the applicable tax returns.
How Can a Short Sale Affect Credit and Future Homeownership?
A short sale, late mortgage payments, and related account reporting may affect credit. The exact effect varies according to the borrower's overall credit history, lender reporting, delinquency history, and future underwriting requirements.
Rules governing eligibility for another mortgage depend on the new loan program, lender, financial circumstances, and guidelines in effect at that time. Homeowners should obtain property-specific guidance from their loan servicer, a qualified lender, and credit professionals rather than relying on a generalized promise.
Can a Seller Receive Money From a Short Sale?
In many transactions, the seller cannot receive sale proceeds because the lender is accepting less than the amount owed. However, some programs or negotiated approvals may permit relocation assistance or another expressly approved payment.
Any payment to the seller or another party must be disclosed and authorized. A seller should never accept an undisclosed side payment, rebate, or agreement outside escrow.
How Is the Listing Price Determined?
The listing price should be supported by current market evidence. Dawn analyzes recent comparable sales, active and pending competition, condition, location, property type, improvements, repair needs, buyer demand, and local market trends.
The lender may conduct its own valuation and require a different price. A well-supported pricing and marketing record helps demonstrate that the property was exposed to the market and that the offer is reasonable.
Why Hire a San Diego Short Sale Expert?
Short sales require a combination of real estate knowledge, documentation discipline, communication, patience, and negotiation. An inexperienced approach can create preventable delays, cause documents to expire, weaken the lender submission, or allow important deadlines to be missed.
An experienced San Diego short sale agent can help:
- Evaluate the property's current market value
- Explain the real estate process and likely transaction stages
- Identify potential liens and complications early
- Develop a realistic pricing strategy
- Market the property professionally
- Screen and compare buyer offers
- Prepare transaction documents accurately
- Organize the lender-submission process
- Track document and approval deadlines
- Communicate with buyers and cooperating agents
- Coordinate escrow, title, HOA, and transaction participants
- Negotiate real estate terms and lender-required changes
- Keep the transaction moving toward an approved closing
Why Work With Dawn Lewis and The Lewis Team?
Dawn Lewis brings more than 35 years of San Diego real estate experience to homeowners facing difficult property decisions. She understands that a potential short sale is not simply another listing. It can involve financial pressure, uncertainty, sensitive personal information, and urgent deadlines.
Dawn approaches the process with straightforward communication, careful preparation, professional marketing, and persistent follow-through. She and The Lewis Team work to ensure that sellers understand what is happening, what documentation is needed, and what the next step may be.
The Lewis Team can help you:
- Review your San Diego property's likely market position
- Understand how a short sale differs from a conventional sale
- Prepare the home for sale based on your circumstances
- Establish a defensible list-price strategy
- Market the property to qualified buyers
- Evaluate offers and transaction strength
- Coordinate the short-sale submission and real estate documentation
- Respond to requests and track lender review
- Work with escrow, title, buyers, agents, and authorized parties
- Manage the transaction through closing if approval is obtained
No agent can guarantee lender approval or a particular outcome. What Dawn can provide is experienced representation, honest communication, organized transaction management, and a focused effort to help you pursue a workable solution.
Frequently Asked Questions About San Diego Short Sales
How long does a San Diego short sale take?
Timing varies. Lender review can take weeks or months depending on the servicer, investor, loan type, number of liens, documentation, valuation, foreclosure status, and buyer. Approval and closing deadlines should always be confirmed in writing.
Can I sell before I miss a payment?
Possibly. Requirements vary by lender and program. Contact the mortgage servicer and appropriate advisors before making decisions about mortgage payments.
Who approves the sale?
The seller accepts the buyer's offer, but each affected lienholder generally must approve the reduced payoff and lien release before the transaction can close.
Can there be more than one mortgage?
Yes, but all liens affecting the sale must be addressed. A second mortgage, HELOC, HOA lien, judgment, tax lien, or other claim may require separate negotiation or approval.
Does a short sale automatically stop a foreclosure?
No. Listing or submitting a short sale does not automatically stop foreclosure. Continue monitoring every notice and consult the servicer and legal counsel about urgent deadlines.
Will I owe money after closing?
That depends on the approval terms, loan, applicable law, and other obligations. Have a qualified attorney review questions about liability and the lender's written approval.
Will canceled mortgage debt be taxable?
It may be. Federal and California exclusions or exceptions may apply, but the result is fact-specific. Consult a qualified tax professional.
Do I still need to disclose property defects?
Yes. A short sale does not automatically remove applicable seller disclosure duties. Complete disclosures carefully and honestly.
Can the lender require a higher price?
Yes. After reviewing an appraisal or broker price opinion, the lender may counter at a higher price or request changes to costs and transaction terms.
Can the seller receive relocation assistance?
Some programs or approvals may allow it, but it is never guaranteed. Any payment must be fully disclosed and expressly approved.
Why should I contact a short sale agent early?
Early contact provides more time to evaluate the property, collect documents, identify liens, market the home, obtain an offer, and respond to lender or foreclosure deadlines.
Contact a San Diego Short Sale Expert Today
If you are worried about your mortgage, owe more than your San Diego property may sell for, or have received a foreclosure-related notice, you do not have to navigate the real estate process alone.
Contact Dawn Lewis for a confidential conversation about your property and the steps involved in a possible short sale. Dawn and The Lewis Team can evaluate the real estate situation, explain the process, answer your questions, and help you determine the next appropriate step.
Dawn Lewis
Short Sale Expert
The Lewis Team at Real Broker
California DRE #01042809
Call or text: 619-656-0655
Website: DawnSellsSanDiego.com
This page provides general real estate information and is not legal, tax, bankruptcy, lending, credit, or financial advice. Short-sale requirements and outcomes vary. Homeowners should consult their mortgage servicer and qualified legal, tax, financial, and housing-counseling professionals concerning their individual circumstances.